
Prepaid cards
Alternatives to credit or debit cards

If you're unable to get a bank account, or want a simple way to limit your spending, then a prepaid card is worth considering adding to your wallet. There's no credit check to pass and you can only spend or withdraw the amount you add to it. This guide has full information, alternatives and our top-pick cards.

First, a quick overview of prepaid cards...
In essence, prepaid cards are quite basic – they allow you to load money onto them, which you can then spend. They can be a good alternative to a debit or credit card, as you can only spend what's on the card and you'll need to have it loaded in advance.
They usually don't require a credit check to apply for, which can be useful if you've got a bad credit score. However, getting a prepaid card doesn't help build your credit score, no matter how carefully you spend. And, although they're widely accepted, there are some exceptions such as for car rentals and pay-at-pump fuel.
| - Minimum age: 18 |
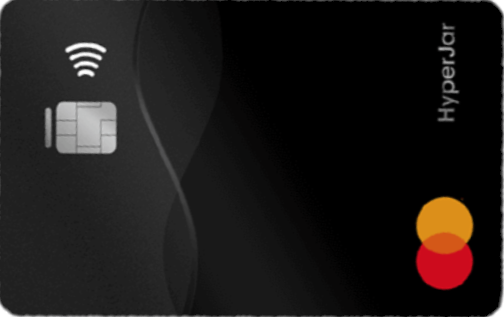
Hyperjar* | - Minimum age: 16 |
What is a prepaid card?

A prepaid card works like a pay-as-you-go debit card. You add money to the card, which can then be used in most places where card is accepted, including online and cash withdrawals. You normally can’t spend more than you’ve loaded onto the card, so you won't be faced with pricey overdraft charges. Unlike most debit cards, it doesn't come with a current account.
There's also no hard credit check involved, so could be a lifeline if you're unable to get a bank account due to a poor credit history or if you're lacking proof of address – though see our Basic bank accounts guide first for the top easiest-to-get accounts.
What are the pros and cons of a prepaid card?
Prepaid cards come with their own set of advantages and disadvantages...
Pros:
✅ Good for budgeting. You can only spend what's loaded on the card, so it's harder to overspend.
✅ Convenience. Like debit and credit cards, prepaid cards are widely accepted.
✅ No credit check. Unlike credit cards or bank accounts, prepaid cards typically don't require a credit check, making them accessible to individuals with limited or poor credit history.
✅ Can limit your losses if shopping online: Using a prepaid card means you don't give a retailer your main debit-card details. If its systems are compromised, only the money loaded onto the prepaid card is at risk — though you should still report any unauthorised payments straight away.
Cons:
❌ Fees. Many prepaid cards come with fees, including activation fees, monthly fees, reload fees, ATM withdrawal fees and inactivity fees. Try to look for cards with low or no fees so more of your cash stays with you for spending. We've more info on these below.
❌ Limited protection if things go wrong. Your money on the card isn't protected in the same way it would be in a bank account under the Financial Services Compensation Scheme, plus you may have fewer rights to refunds if things go wrong. We've more info on both these potential issues in the need-to-knows below.
❌ You don't build a credit history. Using a prepaid card (even if you manage it well) won't help you boost your chances of getting credit in future, as your usage won't be reported to credit reference agencies. See Credit building credit cards and Best first credit card if you've a limited credit history.
❌ You can't use it for all transactions. Some services, such as car rentals and pay-at-pump fuel, may require a credit card (or at least a debit card). See below for how to get around this.
What types of prepaid cards are there?
There are three main types of prepaid card, suiting different purposes:
-
Everyday spending. Best used as a substitute to debit or credit cards as a simple way to stick to a budget – the focus of this guide. They can also be useful if you've a history of poor credit and can't get a debit or credit card. One type is a delegated spending card– see our guide for more info.
-
Travel and overseas use. Offers near-perfect exchange rates for your travel money with no or low fees to spend or withdraw cash abroad. See Prepaid travel cards for full information and our top picks.
-
Under-18s. Cards that allow teenagers to spend in stores and online, while still giving parents a certain level of control. Our Top cards for under-18s compares the best cards and children's bank accounts.
Prepaid card need-to-knows
If you think a prepaid card is right for your wallet, here are our key need-to-knows to consider before getting one.
1. Your money should be safe if the card issuer goes bust
Money on prepaid cards is classed as ‘electronic money’. Prepaid card providers must safeguard customers’ money — usually by keeping it separate from their own operating cash in a dedicated account, though some use insurance or a similar guarantee instead.
So, provided the prepaid card company has followed the rules, if it were to go bust, the bank or building society where your money's held will still retain your cash and you should be able to get it back. But it may take time and you aren't guaranteed to get it back in full, as insolvency or administration fees may need to be deducted.
If the bank or building society holding your safeguarded funds goes bust, you may be covered by the FSCS, depending on eligibility. Always try and find out which bank the provider uses for its ringfenced accounts, so you can then understand the risk. For example, you may think your cash would be safer at a big bank like Barclays or NatWest than at a bank you've never heard of.
Either way, it's best to think of your prepaid card as one that you'll keep cash on for immediate or short-term spending requirements, rather than as a place to store heaps of it for long periods of time.
2. If your card is lost or stolen, tell the provider immediately
Report a lost or stolen card to your provider straight away. It should block the card, and may charge a fee to issue a replacement.If someone makes payments you didn’t authorise, ask the provider for a refund.
It should normally refund you by the end of the next working day, unless it has reasonable grounds to suspect fraud. If you don't report the card as lost or stolen, you may be liable for up to £35 of unauthorised payments made before you told your provider.
3. You may be able to use chargeback protection, but not the powerful Section 75 offered by credit cards
Prepaid cards aren't like credit cards, which offer Section 75 protection as part of the Consumer Credit Act.
However, you'll have access to Visa and Mastercard's chargeback schemes instead. These give you a chance to get your money back if you buy faulty goods, a service isn't provided, or a company goes bust and goods aren't delivered, but successful claims can take time to process. Our Chargeback guide explains how it works.
4. You'll usually need another account to load money onto a prepaid card
Most prepaid cards are topped up by bank transfer or debit card, meaning you’ll usually need another bank account. Some also let you have your salary paid in, or add cash at PayPoint, the Post Office or similar — though this is less common.
Check how your card can be topped up, any limits and whether fees apply before applying.
5. Some places don't accept prepaid cards – always have a backup way to pay
Prepaid cards are generally accepted anywhere you see the Mastercard or Visa symbol, but you may have difficulty using one for transactions that require a security deposit or preauthorisation, such as car hire, hotel bookings and at some petrol stations.
And even if you are able to, you may not want to. When you offer a card for a deposit, the company will 'lock' funds on the card for the duration of the hire and you won't be able to use it until the final bill has been settled and cleared. So, if you can, use another card as a security deposit, preferably a credit card.
6. Take note of fees – some cards charge for not using them
Fees vary widely, so check the tariff carefully before applying. Look out for:
-
Application or activation fees to open the card.
-
Monthly fees — some cards charge nothing, while others charge a regular account fee.
-
Purchase transaction fees — ideally choose a card that does not charge each time you spend.
-
Cash-withdrawal fees — these can be a fixed amount, a percentage of what you withdraw, or waived entirely.
-
Top-up, spending and withdrawal limits — particularly important if you will need to add or withdraw larger amounts.
-
Inactivity fees if you do not use the card for a set period. Check what activity, if any, resets the fee.
-
Renewal or replacement-card fees when the card expires or is lost.
-
Fees to return unused money when you close the card. Some providers charge for this, though regulated e-money providers face legal restrictions on redemption fees.
Choose a card based on how you expect to use it, and close it if you no longer need it.
How to choose the best prepaid card for you
As we've mentioned, prepaid cards can serve a variety of functions, so it's important to pick a card that best suits your needs. Here are some things to consider:
-
Be aware of fees. Some cards will have a monthly fee – is it worth the price? Others will charge specifically for withdrawing from an ATM or making transfers. Consider what you'll use the card for and ask whether you'll be getting your money's worth. We've more info on prepaid card fees here.
-
Going abroad? If you plan on using a prepaid card for your travel money when you're on holiday, get one that can convert currency ahead of time and avoid ones that charge for spending or withdrawing in foreign currencies. See our full guide to Prepaid travel cards.
-
Do you need a prepaid card? A standard current account with debit card is usually the best choice for most people. It can give you perks, such as interest, cashback, branch access or an overdraft (subject to eligibility). If you can’t open a standard bank account, try a basic bank account that comes with a debit card. They're aimed at those with low credit scores or limited credit history and are much the same as a standard bank account, but without an overdraft.
Top-pick prepaid cards
Here are our top prepaid cards suitable for everyday spending in the UK, based on the lowest fees and/or perks. For other uses, see our guides on Prepaid Travel Cards and Cards For Under-18s.
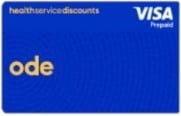
Account info: | Decent pick if you work in charity, education or healthcare (including carers), though watch out for fees. If you work in one of these sectors, the Ode prepaid card gets you cashback at over 70 retailers, including Asda, Boots, Sainsbury's and Waitrose (though do note you can't withdraw cash on this card from ATMs). After an initial £4.99 to get the card, you can add credit (min £20) to your card online or via its app with the funds available instantly. After the first year, a £2.99 annual fee kicks in, so diarise to cancel if you find you're not earning much cashback from it. There's also a £5/mth inactivity fee after 12 months of no usage, so make sure you cancel before that takes effect. |
HyperJar* | No monthly fee and a variety of budgeting features – though usage fees can apply and the card can't be used at ATMs. The HyperJar card* allows you to set up 'spending jars' and 'shared jars' within the app, to help you budget, though you can't withdraw cash using this card. You also get cashback when buying vouchers for various retailers, including Amazon. There are a few limits to be wary of. For example, transferring money out to a bank is fee-free four times a month. Loading the card with less than £10 is free just once a month, though you can add loads of £10+ fee-free 10 times a month. If you exceed any of these limits, you'll be charged £1 a time. |
Updated November 2026. Important. The providers above are authorised by the Financial Conduct Authority. Any money you deposit in Clubcard Pay is covered by Tesco Bank's FSCS protection. For Ode and HyperJar, it's ring-fenced in a separate bank account, so if there are problems with the provider, the money's safe (though it wouldn't be if the underlying bank went bust, so it's best not to leave large balances on these cards, just in case).
Cashback sites may pay you for signing up
As an extra boon, members of specialist cashback websites can be paid when they sign up to some financial products. Do check that it's exactly the same deal though, as terms can be different. Remember, cashback is never 100% guaranteed until it's in your account.
Full help to take advantage of this and pros & cons are in our Top cashback sites guide.
Prepaid card FAQs
Can prepaid cards help me build or repair my credit score?
No. Unlike credit cards or even some bank accounts, prepaid cards don’t report your spending to credit reference agencies, so using one responsibly won’t usually help build your credit history. A basic bank account can help you establish a financial footprint and manage bills, but it won’t build a borrowing repayment record in the same way as a credit-builder card. If your main aim is to build credit, look at credit-builder cards instead.
Can I have my salary or benefits paid directly onto a prepaid card?
Some prepaid card providers do let you have wages, Universal Credit, or other benefits paid directly onto the card (they’ll give you an account number and sort code). But not all do – check before applying, and make sure there aren’t hidden fees for incoming payments.
Are prepaid cards safe to use online?
Generally, yes. Prepaid cards work much like debit or credit cards for online purchases, so you can use them on most sites. They also give you chargeback protection if something goes wrong, though not the stronger Section 75 protection you’d get with a credit card.
Can I go overdrawn with a prepaid card?
No. Prepaid cards are designed so you can only spend what’s on the card. If there isn’t enough money loaded, the transaction will simply be declined. That makes them handy for budgeting, but also means you’ll need to top up regularly to keep using them.
Share this guide?