

The Budget Planner
How to manage your money

The problem with most budgets is that they don't work. While they look at a typical month's spending, what about birthdays, that dentist visit and other one-offs? This guide gives you tips and tricks and includes a free Budget Planner, which analyses your finances to help you manage and control your cash.

How to use our Budget Planner tool
Our Budget Planner is based on rock-solid budgeting theory, accurately mapping your incomings and outgoings over a year, then helping you assess whether your budget balances. Here are some brief pointers on how to get started:
1. Gather online or paper bank statements, household and utilities bills, and receipts. Lay the groundwork for a monthly budget by compiling these financial records, as well as information on credit card debt, pension contributions and one-off spends.
2. Fill in the free Budget Planner tool (or download the spreadsheet version). Be detailed and realistic when filling in your answers – remember it's better to overestimate than underestimate. You can complete our free Budget Planner online in one go, or download and fill out the spreadsheet version.
3. Got an overspend? It's time to reduce your spending through pain-free savings (cutting bills without cutting back) – think credit cards, broadband, childcare, Council Tax etc. If that's not enough, try painful savings – essentially, making lifestyle changes (our spending Demotivator tool could help).
4. Need some help sticking to your personal budget? Use our 'piggybanking' technique. This involves dividing your money into different pots, each dedicated to a different types of spending (such as groceries and birthday presents). That way, you'll know exactly how much you have to spend on each category.
Why is budgeting important?

For many people, budgeting is more crucial than ever before. With the cost of living putting pressure on household finances, a budget can help you manage your money and find ways to save. It also answers two key questions...
Do I spend more than I earn?
An instinctive assessment is easy – if you're eating up your savings or building up debts, you're likely to be overspending. But before you can address this, it's important to get an accurate idea of the size of the problem.
It may not seem fun to track expenses, but major overspending can lead to a debt spiral and severe problems, that's why the Budget Planner is designed to give you a definitive assessment of your finances and where your money goes.
What can I afford to spend?
Once you know where your money is going, you can start to prioritise your spending to live within your means. You'll better understand whether you could be putting money aside in a savings account to save for a big purchase, or whether you need a plan to deal with debt.
While the Budget Planner helps you prioritise your spending, the hardest part can be sticking to your budget. The piggybank technique is designed to help you do just that.
Before you start, read the following six tips to help you fill in the free Budget Planner spreadsheet below.
1. Gather together all bank statements, household bills and receipts
Don't be tempted to guess or estimate. The success of a budget relies on accurate figures for your income and spending. The only way you can be as sure as posisble is by getting all your bank statements and household bills in front of you.
Also, while getting an idea of monthly spending is great, I recommend at least three months' worth of bills and receipts so you can keep track of any quarterly expenses, such as a TV licence or water bills.
2. Decide who your budget is for
It's very important to be consistent when budgeting. First, decide who you're filling it out for – is it just for you and your personal finances, or is it for your partner/family too? Finances can't always be separated, in which case you should sit down and do it together.
3. Be as accurate as possible with your figures
It's tempting to try to fool yourself by underestimating your expenditure. Try to be accurate, and, if you're not sure, estimate higher rather than lower – that way, you'll have cash left over.
Some types of spending overlap across different groups, so don't count the same expense twice. For example, if you've included your car insurance in the motoring section, don't include it again under insurance.
4. Distinguish between credit card 'debt' and 'spending'
The credit card section is designed for you to enter the cost of repaying your existing credit card debts. Don't confuse this with spending, where you simply use your credit card and pay it off IN FULL.
The best way to explain this is with an example. Say you spend £500 each month on food shopping using your credit card, but then pay off your bill in full. This spending belongs in the food shopping category, not in the credit card category. Otherwise, you'll be counting it twice.
5. Check your pension details
If you contribute to a pension through payments from your bank account each month, include these in the expenditure section.
However, if your pension contributions are deducted directly from your salary, don't include them again. In the income section, enter the net amount of pay you receive after all deductions.
6. Don't forget to include 'one-off' spends
The MoneySaving way of accounting for these is to spread the annual cost across monthly amounts.
So let's say your new car costs £2,000 – over a year, that's about £166.67 a month. So you'd put £167 under "new car" each month.
Another top tip is to remember that when you include one-offs, such as holidays, you should also account for any regular spending you'll avoid.
For example, say you normally spend £100 a week on food shopping and £30 on petrol. If you're abroad for the week, you won't spend this, so make sure your budget reflects that.
What's different about my budgeting technique?
It's often said, "in debt? Do a budget!", "Skint? Draw up a budget!", "Need to save for something big? (for example, a car, wedding, baby on the way) BUDGET!" But while budgeting is seen as a solution, unfortunately most budgets are worthless.
The main problem is that they concentrate on a typical month, and massively underestimate your spending by missing huge costs such as Christmas, summer holidays, new sofas or getting a new car.
Broad categories such as "motoring" make it too easy to forget the small expenses that add up. Instead, "motoring" should cover MOTs, new tyres, petrol, insurance, breakdown cover and more. Hopefully the Budget Planner counters that by having nearly 100 separate categories.
The free Budget Planner
It's always surprising to see how many things you spend money on. Worse still is how much you spend on them.
Leave anything that doesn't apply to you blank. We'll treat it as £0. Enter each cost or income once, choose whether it's weekly, monthly or yearly, and we'll convert it to a monthly figure.
Your progress won't be saved online, so aim to complete it when you have time to do it all in one go.
Once you've entered your figures, you can download your completed budget and results as an editable spreadsheet to save and keep working on offline.
Want to download it instead? Download a blank Budget Planner spreadsheet (downloads as a Microsoft Excel file) to fill in and save on your computer.
The Budget Planner
A simple tool to show what comes in, what goes out, and what you've got left each month.
Leave any field that doesn't apply blank – we'll treat it as £0. Enter each amount once only and choose whether it is weekly, monthly or yearly. Your progress won't be saved, so complete it in one sitting. You can then download your completed budget as an editable spreadsheet to save and continue offline.
Your figures are calculated as you go, but your total is revealed when you're ready.
What your result really means...
Your monthly budget result
Providing you've been honest with yourself, it's time to relax a little – but MoneySaving doesn't stop there. In fact, it's just the beginning. Paying less for things means you have more money in your pocket to enjoy life more (and possibly set some financial goals and save some for the future too!).
Savings from doing this could be £3,000 – £5,000 a year. My estimate is it'll take a full day's work... but look at the return. It'll be the best paid work you've ever done. The whole MoneySavingExpert site is dedicated to doing this in every area of your lifestyle, but to get started, read the Money Makeover article.
Spending more than you earn may not seem like a big deal, yet it's a potential disaster – and not just financially. At best, you're eroding your savings; at worst, you'll need to borrow.
Such borrowing is also the worst, as it means you can't afford your lifestyle and thus there's no planning to the debt and no end in sight. Sadly, I've seen this result in debt crisis too many times, and that doesn't just hit your pocket – it can hurt your home, family, mental health and relationships.
Prefer to fill it in by hand?
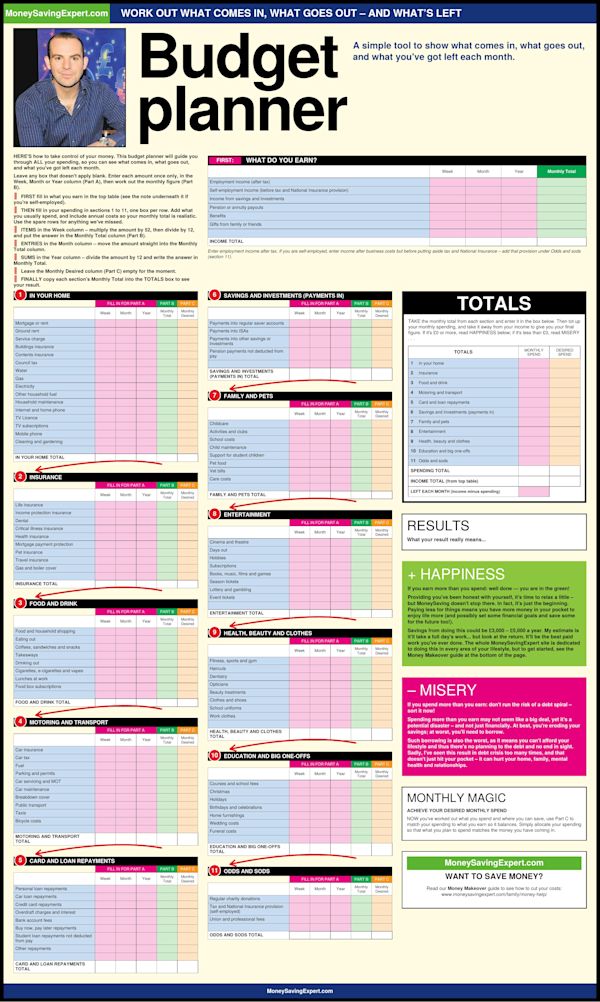
Martin’s original Budget Planner, first published in a national newspaper well over a decade ago, was hugely popular. We’ve recreated it with today’s spending in mind – for example, streaming’s in and video rentals are out.
Put it on the fridge or noticeboard and get everyone in the household involved. It’s a simple way to see where the money goes and make decisions together.
Click print for an A3‑sized version. It’s set up as two A4 pages you can stick together, so there’s no need for a special printer.
MoneySave as you go!
Are you getting the best value for money? Can you cut costs? The Money Makeover will help.
What is a 'debt spiral' and why does it matter?
A debt spiral is when your debt keeps growing and you can't afford to repay it.
If you consistently spend more than you earn and need to borrow to cover your costs, you run the risk of entering a debt spiral. It works like this:

This isn't over-dramatising. When there's no money left and you can't borrow more, while the creditors are asking for money back that you've no ability to repay, it touches every part of your life.
What to do if you've got an overspend...
I've got a number of simple steps to go through to try to reduce the amount you're overspending.
Step 1: Pain-free savings – cut bills without cutting back

This is about ensuring you live the same way, but pay less to do so. It's pain-free, as no lifestyle changes are needed.
Don't just look at the obvious things, such as credit cards, broadband and mortgages. You can save on childcare, Council Tax and your supermarket shopping too. To go through this in detail, use the full step-by-step Money Makeover guide, which shows you how to look at everything.
Step 2: Re-budget with what you expect to save
It's worth revisiting your Budget Planner, incorporating your revised spending after making the pain-free savings. What you do next depends on the result...
Are you currently spending within your means? Congrats, no more change needed (unless you're saving up for something), but keep monitoring your finances. Effective budgeting is still worthwhile. See piggybanking.
Still spending more than you earn? Then it's time for step 3...
Step 3: Painful savings – cutting back
You need to spend less, do less and sell things until you're living within your means. We've got more detailed guidance in Debt problems & help available.
Start small. Easy lifestyle changes can make a big difference. Check out The Demotivator to see the real impact of small spending changes. Cutting out your £4 weekday coffee could reduce your annual expenditure by more than £1,000 for example.
Ask yourself two questions for every aspect of your life:
1. Do I need it?
2. If I do, could I do it more cheaply?
This may mean having the self-discipline to cut out cinema trips and expensive Christmases, half-compromises like switching Sky for Freeview, or stopping costly holidays abroad in favour of holidaying at home. See the Stop Spending guide for full help.
Don't be afraid to sell things. If you're asset rich but income poor, then consider flogging things you don't use or need. Of course these sales are one-offs, but hopefully you can use the money to repay debts or get your savings back together. Though be aware there's a limit on how much you can earn tax-free from selling online.
It could include selling things like a car or motorbike, working through your wardrobe and getting shot of old clothes (see the eBay Sellers guide), or selling old mobiles. If you've got it and don't use it, consider flogging it.
Are your debts severe?
If things are so grave that even this doesn't touch the sides, you're likely in serious debt and need urgent guidance. Visit free non-profit debt crisis agencies like Citizens Advice Bureau, StepChange Debt Charity or National Debtline quickly.
Boost your budgeting success by piggybanking
Doing a budget on paper is easy, the difficult bit is sticking to it. That takes either strong discipline or a decent technique. I can't help you with the first, but I have a simple yet powerful method to help you take control of your spending. It's called piggybanking.
There are two key facts you need to understand before you start to budget properly.
1. Don't rely on your bank balance
Your bank account shows you a simple snapshot of the scene that day. Less obvious is what payments are due in or out and when direct debits are paid, let alone when you need to go shopping.
These days a lot of banks do have basic monthly budgeting systems available that work out what you're likely to have left to spend after you've paid your expected bills. This is better than nothing, but still doesn't provide the full picture.
These tools only look at a typical month and don't take into account one-off expenses or long-term savings goals. If you only rely on this for your budgeting, you're going to end up overestimating how much you can comfortably spend.
2. Don't ask 'what's cheapest?' Ask 'what can I afford?'
To get back on track, your finances must lead your lifestyle, not vice-versa.
Many people look for the cheapest way to do something, and consider that to be MoneySaving.
But if you're overspending, it's more important to cut back so you can live within your means.
Let me clarify this with an example. People often get themselves into trouble at Christmas time by asking: "How do I have a great time, with a big tree, all the family round for dinner and hi-tech pressies for all the kids on the cheap?"
This is a bad question. It establishes your priorities without reference to how much money you've got. The right question to ask is: "What can I afford to spend this Christmas?", and then plan your activities around that.
What is the piggybanking technique?

The piggybanking technique helps you automate your spending so you always know how much money you can truly spend.
It's easy to do:
Step 1: Select your main categories of spending
The aim is to have your books balancing – so you're not spending more than you earn. To do that, you need to work out how much you can spend on different areas of your life. This could include housing costs, utilities, groceries, savings, loans and debt payments, transport, school costs, birthdays and holidays, subscriptions – as well as any going out or 'fun' money.
Once that's done, you need to scan through to see what the major categories are. If you're self-employed, you should always have one for any tax you'll owe.
Step 2: Arrange your piggies
Now you know how much money you want to spend on different items, the aim is to make it as simple as possible to know how much cash you have available.
There are a few ways to do this. It used to be you'd have to set up a couple of different bank accounts, one for each of your categories, so the money's effectively in little pots (almost as if you're putting them in different piggybanks). For example, to help with your savings goals you could have a main bank account, a bills account, then accounts for holidays, Christmas, and emergencies.
However, many current accounts now offer simpler and quicker ways to split money into different pots that can be easily managed in one place, either via an app, or online. So you don't need to worry about having lots of bank accounts with different providers.
Some of the banks that offer apps with piggybanking features include Chase*, Monzo, Revolut and Starling.
Other more traditional banks will often let you open other 'savings' accounts (paying little or no interest) and let you easily set up standing orders between them. Explore the full best bank accounts guide to find the right option for you.
Bonus tip: for the piggies you're only likely to access once a year, for example, holiday or Christmas piggies, it's worth using a savings account so that you're accumulating interest on the money you're putting in there. Our Top Savings Accounts guide will point you in the direction of the best options for this.
Step 3: Use a standing order to feed the piggies
Now you've divided your money into separate pots, either by setting up separate bank accounts, or by using an online platform or app, it's time to feed each of the piggybanks – including the bills account, which you should always overestimate slightly – from your main account. Set up standing orders to shift the right amount of cash each and every month.
As an example, if you allocated £800 a year to spend on Christmas (the average amount for a UK family), you would put £67 a month into a Christmas account, so it builds over the year.
Tip: Schedule this for two days after getting paid, not for the same day – just to give you a little bit of room in case there are any payment problems.
The result: Now your bank account(s) tell the whole truth
Now, when you look in your main account, you know it really shows how much you have to spend, as all the money for bills and other key areas has been shifted out.
Plus, if you see a £700 holiday, but there's only £400 in your holiday account, you now KNOW you can't afford it and can cut your cloth accordingly.
Once you've piggybanked, you can spend the leftovers
If you've piggybanked properly, putting aside all the cash you need for bills and essentials, you're free to spend whatever is left in your main bank account each month. You really know how much money you have to spend at Christmas or to go on your holiday – there's no fooling yourself anymore.
Important: It's possible the end result of this is you can't afford the holiday you wanted. But more importantly, you won't spend what you can't afford and wind up in the debt spiral.
Share this guide?